


Business Sectors
Business Sectors
Events
Contents

Westwood: Mexico jack-up count set to rise
As of mid-August 2026, global offshore rig utilisation is showing some signs of strengthening standing at 87%, according to Westwood Global Energy Group, RigLogix director, Teresa Wilkie


PEMEX Continues Operation Re-Starts with Some Jackups Following Suspensions
In Mexico, the rig count has fallen sharply over the past two years as the Mexican national oil company, PEMEX, grapples with mounting financial pressures and a tightening capital budget. The company accumulated significant debt and struggled to pay contractors on time, creating cash flow challenges throughout Mexico’s offshore supply chain. As a result, drilling activity was scaled back, and many service providers were becoming reluctant to keep rigs operating without greater certainty around payments. During the second half of 2025, catch-up payments started being made and some rigs started returning to work.
A major consequence of these financial difficulties was the suspension and cancellation of offshore drilling contracts. Several contractors, including Borr Drilling, Paratus Energy Services, Perforadora Mexico and others, saw rigs temporarily idled or contracts terminated as PEMEX sought to reduce expenditure. RigLogix data shows that the number of units operating in Mexican waters for the NOC fell from 30 units in August 2023 to a low of about 15 by mid-2026 before beginning to climb back up and reaching 18 currently.
Recently the operator has been making more moves to combat the decline in its rig count with contract extensions awarded to Borr Drilling jackups out through 2Q 2030, as well as the resumption of four contracts for Perforadora Mexico jackups following suspensions that began in late 2024. Further, there have been indications that PEMEX may also have a requirement for up to five jackups, though timing and duration of contracts has yet to be determined.
Looking ahead, a continued recovery in Mexico’s jackup market looks likely, however, the extent will depend largely on PEMEX’s financial health and its ability to restore confidence among contractors. While offshore rig demand remains robust in other regions such as the Middle East and Southeast Asia, Mexico’s shallow-water market is likely to remain subdued until more outstanding supplier payments are addressed, and drilling budgets begin to recover.
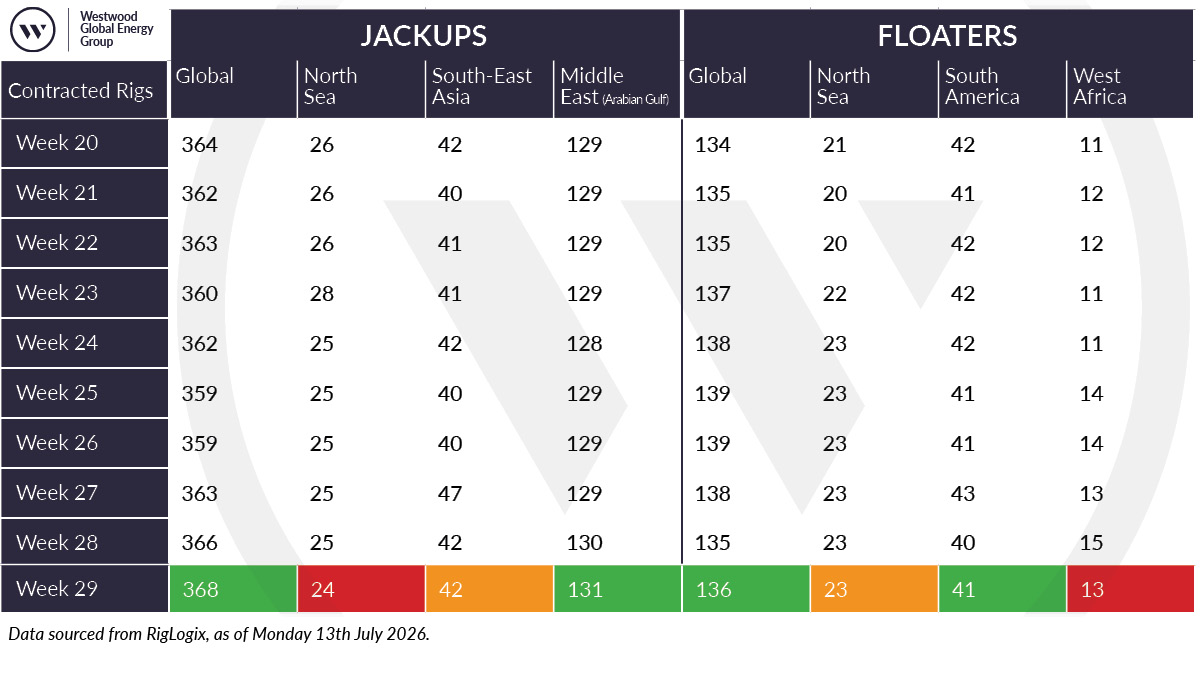
Globally, offshore righ utilisation has seen a two percentage-point increase versus last month but a decline of 3% versus the same period in 2025.
The floating rig market has meanwhile remained flat, with combined drillship and semisubmersible utilisation holding at 87%, unchanged from the previous month and in line with levels seen a year earlier.
Within the floating fleet, drillships continue to outperform, achieving utilisation of 90%, when including units with future contracts, while semisubmersible utilisation trails at 82%. This gap reflects the stronger demand for drillships in key deepwater markets, while semisubmersible activity remains more varied across regions and operating environments.



Related to this Story
Events
Maritime Regulations Webinar Week
 16 Dec 2025
 GMT - ONLINE
Floating energy: successfully unlocking stranded gas using FLNGs and FSRUs
24 Feb 2026GMT - ONLINE
© 2026 Riviera Maritime Media Ltd.


