


Business Sectors
Business Sectors
Events
Contents

Westwood rigs round-up: harsh-environment semisubmersible market close to sold out
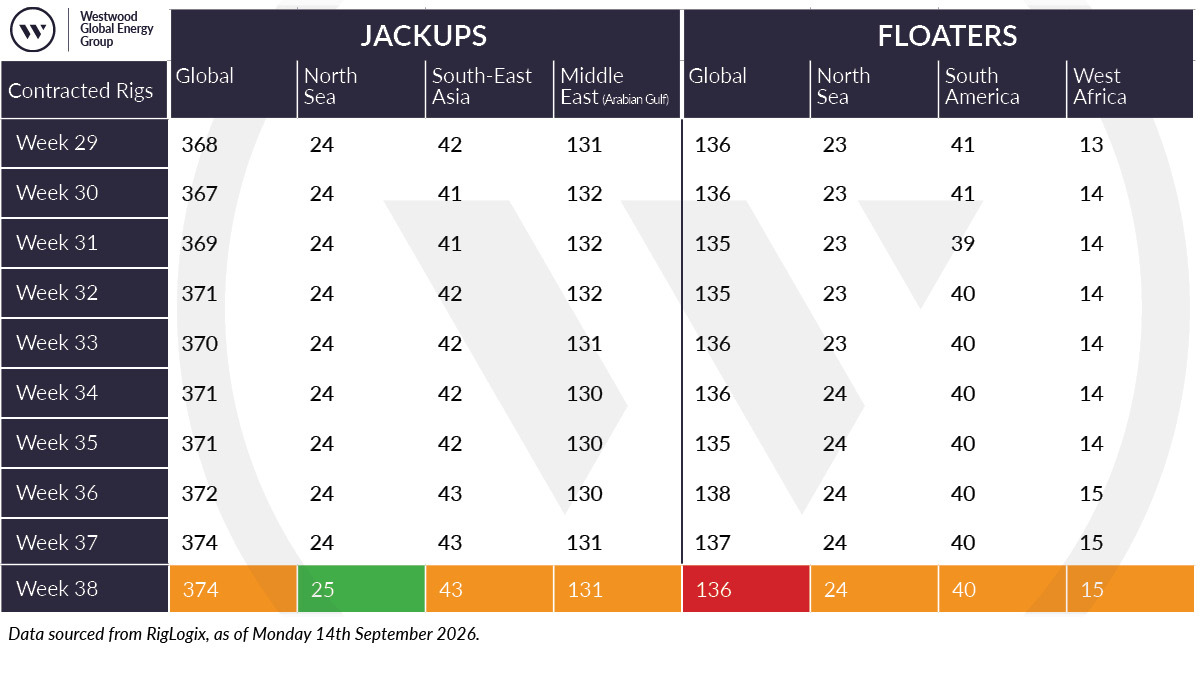
Marketed global offshore rig utilisation has remained at 87% for five consecutive months, indicating an overall levelling out of the supply and demand balance, according to Westwood Global Energy Group, RigLogix director, Teresa Wilkie


For the jackup segment as of mid-September 2026, marketed utilisation is currently 87%, which is unchanged versus the same period in August 2026, but is a three-percentage-point decrease versus September 2025. This is due to ongoing challenges presented by the conflict in the Middle East, as well as lower demand for other key regions such as Mexico and India.
The floating rig market, which combines drillship and semisubmersible supply, has meanwhile recorded a one-percentage point increase versus August, and is currently sitting at 88%. When broken out separately, the drillship market has been recording the most gains month on month, rising from 90% in August to 93% this month. There are 81 of the 87 marketed units committed for work currently or have future work in place.
For semisubmersibles, utilisation has fallen for four consecutive months and is now sitting at just 82%, with 59 of the 72 marketed committed for work. This gap between the two floating rig segments continues to reflect the stronger demand for drillships in key deepwater markets, while semisubmersible activity remains more varied across regions and operating environments.
Harsh-Environment Semisub Market Near Sold Out
While overall semisubmersible utilisation remains relatively flat, the harsh-environment segment continues to tell a very different story. RigLogix currently tracks 38 marketed harsh-environment units worldwide, of which 37 are either actively contracted or have future work in place giving a marketed utilisation of 97%.
This leaves just a single rig without a confirmed future commitment: Northern Ocean’s 6th-generation ultra-deepwater semisubmersible, Deepsea Mira. However, even that lone gap may soon disappear.
Market sources indicate the rig is edging closer to securing a new assignment beyond its current stacking area in West Africa, further underlining the exceptionally tight conditions that persist within the harsh-environment fleet.
This is a result of increasing demand for such units outside of the traditional areas of the UK and Norway. Of course these are still two essential markets, especially the latter, which accounts for 49% of demand today. However, there are also rigs with commitments in Australia, Canada, China, India, the Falkland Islands and Brazil.
Meanwhile, the outlook for semisub demand (harsh environment and benign environment) also remains strong with a pipeline of tenders and pre-tenders already in the market for campaigns in countries such as the UK, Norway, Australia, India, Canada, Brazil, Myanmar, Mexico, Oman, Peru, Suriname, Libya, Japan, South Korea, Indonesia, Venezuela, Vietnam and Malaysia to name a few.
Because of this high utilisation figure and limited or readily available additional supply of rigs, dayrates remain strong, especially for 6th generation, premium assets such as those capable of operating in Norwegian waters. Dayrates for such top tier assets have been secured this year at a range of $437,000 to $513,000 per day.



Related to this Story
Events
Maritime Regulations Webinar Week
 16 Dec 2025
 GMT - ONLINE
Floating energy: successfully unlocking stranded gas using FLNGs and FSRUs
24 Feb 2026GMT - ONLINE
© 2026 Riviera Maritime Media Ltd.


