


Business Sectors
Business Sectors
Events
Contents

Register to read more articles.
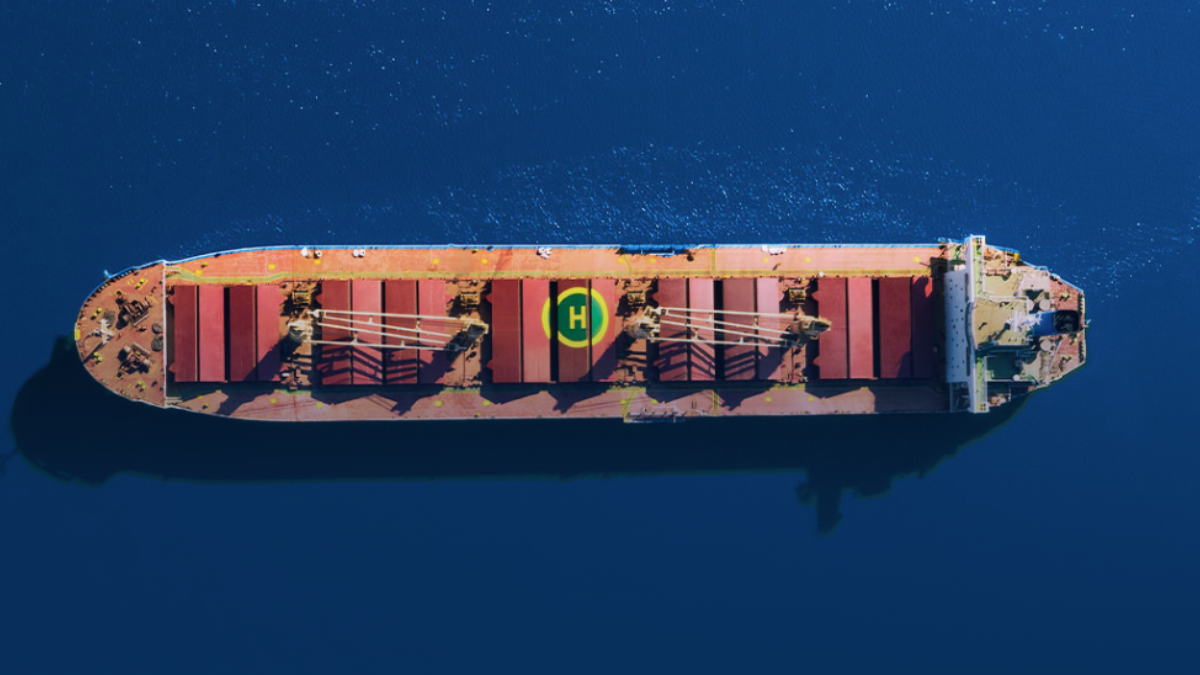
Strong freight market fuels dry bulk S&P, defying summer lull
The dry bulk sale and purchase (S&P) market has gained momentum in recent weeks, bucking the usual summer slowdown as buyers remain active


“The dog days of summer? The holiday armistice is not really happening this year,” Hartland Shipping Services noted in its latest weekly report. Atypically for the season, the S&P market has been lively for bulkers, with firming prices evident and failed sales fixing higher, Gibson Shipbrokers added.
Cleaves Shipbroking’s Einar Straume told Riviera the primary driver is straightforward: strong freight rates.
“Many buyers who would normally wait for a softer summer market and plan to ‘buy the slump,’ are running out of patience and deciding to move when they can,” Mr Straume said.
He also added spot earnings underscore this sentiment. Average daily rates stand in the upper US$20,000s for Capesizes, US$15,000 for Kamsarmaxes, and US$17,000 for Ultramaxes – levels uncommon for July and August.
“Adding to the spot market, we also see strong FFA rates, so there is no incentive to wait either,” Mr Straume added.
Notably, asset values have trended downward this year. According to Xclusiv Shipbrokers, prices across all bulk carrier sizes and ages have dropped between 1% and 21% year-on-year, with Kamsarmax and Ultramax units recording the steepest declines.
Handysize vessels lead S&P activity
Xclusiv’s latest weekly report shows 469 bulk carriers changed hands between January and mid-August, down 13% from 537 in the same period of 2024 due to a slow start to the year.
Handysize vessels account for the largest share, with 122 units sold. Supramaxes follow with 108 transactions, while Panamaxes rank third at 58. Year-on-year, Handysize and Supramax sales fell 11% and 16% respectively, while Panamaxes were the only segment to record growth, with activity rising 26%.
Capesizes and Newcastlemaxes saw the sharpest declines, with 34 and 9 vessels sold so far in 2025 – down 45% and 68% year-on-year.
So far in 2025, activity has centered on mid-age and vintage vessels. Ships aged 11–15 years accounted for 215 sales, or 46% of all transactions, while the 16–20-year-old bracket followed with 99 sales.
Strong dry-bulk freight markets and resilience during the summer lull reflect underlying shifts in cargo flows and operational strategy—topics explored under port congestion, vessel performance data, and minor bulk opportunities during Session 4 at the International Bulk Shipping Conference 2025. View the full programme here.




Related to this Story
Events

Maritime Regulations Webinar Week
 16 Dec 2025
 GMT - ONLINE

Floating energy: successfully unlocking stranded gas using FLNGs and FSRUs
24 Feb 2026GMT - ONLINE
© 2026 Riviera Maritime Media Ltd.


