


Business Sectors
Business Sectors
Events
Contents

Register to read more articles.
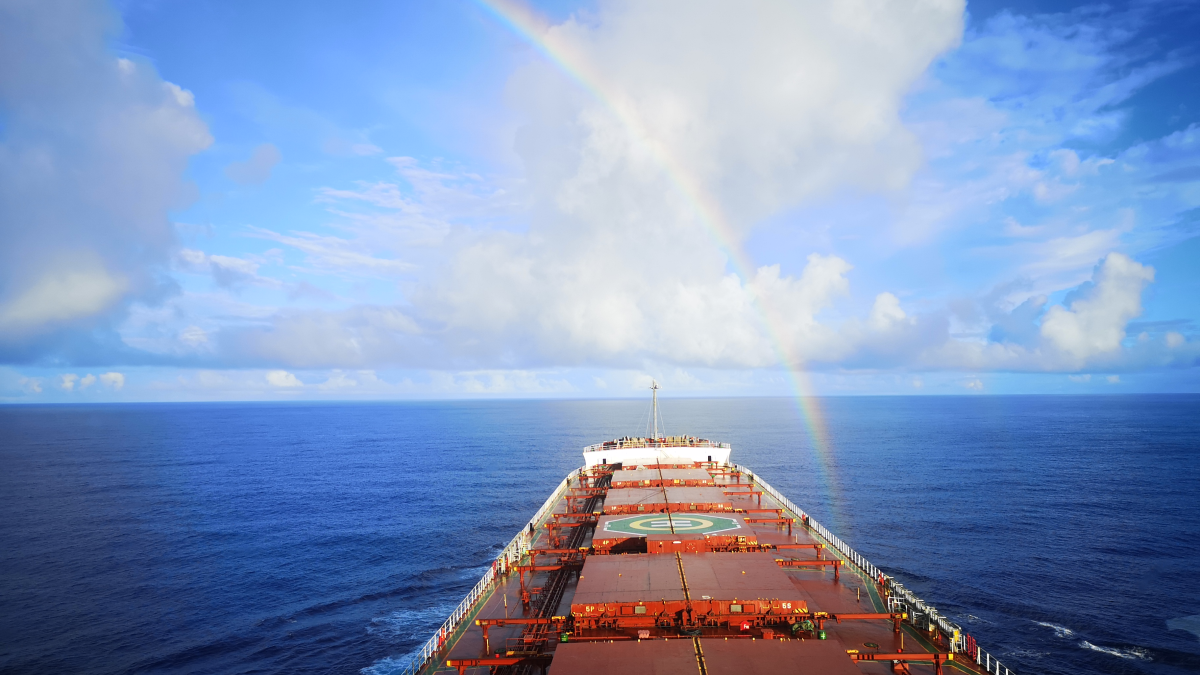
Bulk carrier asset values have been softening: here's why
Asset values in the dry bulk sector are showing signs of correction after reaching multi-year highs in recent months


Head of dry bulk research at Howe Robinson Partners, Bilal Muftuoglu, told Riviera that prices for Panamax, Supramax and Handysize vessels have been gradually declining. Additionally, Capesize values have stabilised and they are no longer increasing.
According to this week’s shipbroking reports, Panamaxes aged between five and 15 years are now valued 5% to 10% lower compared with last month, and 3% to 9% lower over the past three months. Supramax values have also softened, with declines ranging from 1% to 9% in the last month and 1% to 11% over the last three months. The largest decreases have been seen in 10-year-old vessels in both categories, while smaller losses are reported in the Handysize segment.
Meanwhile, Capesize secondhand prices remain resilient, except for 15-year-old tonnage, which has experienced slight declines.
Weaker S&P activity
Explaining the factors behind this trend, Mr Muftuoglu cited a slowdown in secondhand sales. “Aside from the usual summer lull, Q3 has been weaker than in recent years,” he said.
Howe Robinson’s data shows that 119 bulk carriers have changed hands from July to the third week of September, down from 162 in Q3 last year and below the 2019-2022 average of 149 for the period.
Capesize vessels have experienced the sharpest drop, with just 15 sales this quarter, down 17 year-on-year. Supramax/Ultramax sales have also declined, with 36 transactions compared with 53 last year. Panamax sales have seen a more modest decrease, from 33 in Q3 last year to 24 this year, while Handysize deals have remained stable at 44.
Mixed outlook for sub-Capesize vessels
Mr Muftuoglu pointed out these numbers, along with a "less optimistic outlook for the sub-Cape segment," have contributed to the dip in asset prices.
The future for Panamax vessels presents mixed signals. On the positive side, demand in the Pacific is expected to grow, driven by southeast Asia’s increasing grain and coal imports. Additionally, prospects for Indian thermal and met coal are looking constructive, which should support the Panamax Pacific outlook, even in the event of a peak in Chinese imports.
However, the Atlantic market offers a less favourable short- and mid-term outlook. "European coal demand is unlikely to recover unless a major energy disruption occurs, which will continue to pressure rates," Mr Muftuoglu added.
Rising orderbook
Another "concerning" trend is the rising number of new deliveries expected in the dry bulk sector, particularly for sub-Capesize vessels.
Howe Robinson data reveals the bulk carrier orderbook has surged from 610 vessels to 1,273 over the past 3.5 years. Notable ordering activity has been seen in 2024, especially in the Kamsarmax category, which has been bolstered by recent deals from Cosco.
Mr Muftuoglu emphasised the substantial newbuild deliveries expected in the Supramax/Ultramax and Handysize categories in 2024 and 2025 could offset growing demand for minor bulk cargoes, impacting long-term prospects for these vessel sizes.
According to Howe Robinson, the Handysize orderbook grew by eight vessels between January and September this year, while the Supramax/Ultramax and Panamax/Kamsarmax orderbooks increased by 56 and 59 vessels, respectively.
Conversely, the Capesize orderbook remains low, with 110 vessels currently under construction – slightly up from 106 in January but down from 115 at the start of last year. Overall, prospects appear positive for larger tonnage, supported by strong supply and demand fundamentals.
Riviera’s International Bulk Shipping Conference will be held in London, 19 November 2024. Click here for more information on this industry-leading event.




Related to this Story
Events

Maritime Regulations Webinar Week
 16 Dec 2025
 GMT - ONLINE

Floating energy: successfully unlocking stranded gas using FLNGs and FSRUs
24 Feb 2026GMT - ONLINE
© 2026 Riviera Maritime Media Ltd.


