


Business Sectors
Business Sectors
Events
Contents

Register to read more articles.

Newbuilding orders continue to smash records, with spending topping US$177Bn
Shipping is reliving the 2007 newbuilding boom this year, with contracting climbing to record levels and tankers emerging as the undisputed leader in terms of deals


Shipbroker Clarksons said in its latest update that 2026 is on track to be a historically strong year for newbuilding contracting.
Firm orders between January and August stood at 2,128 vessels of 59.7M CGT, running at a similar pace to the record levels seen in 2007 and double the 10-year average.
“Strong newbuild demand comes amid a prolonged period of positive cross-sector shipping market conditions, while fleet renewal requirements also offer underlying support, with appetite firm across the major shipping segments,” analysts said.
In terms of spending, investment has also reached exceptionally high levels. Clarksons estimates that around US$177.2Bn has been invested in newbuildings so far this year, up 31% year on year and on track to match the 2007 record in nominal terms.
“Spending has been supported by firm contract volumes and rising newbuild prices,” the brokerage said.
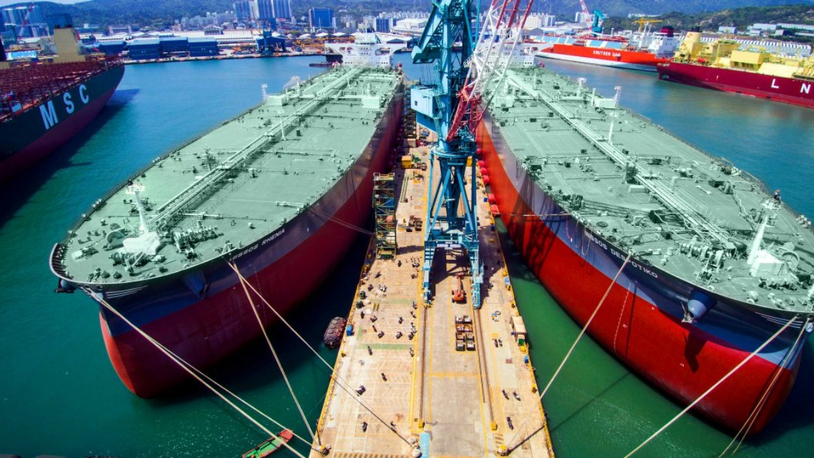
Tankers are leading the race, with Clarksons reporting 646 vessels of 86.8M dwt contracted between January and August, making 2026 already the strongest year for tanker ordering in two decades.
Crude tankers dominate, with 272 vessels totalling 67.7M dwt ordered, the highest volume since 1973. Product tanker demand has also remained firm, with 236 units totalling 16.4M dwt, while the chemical tanker segment has seen orders for 138 vessels of 2.6M dwt.
However, activity remains elevated across the shipping spectrum. Clarksons has recorded orders for 403 bulk carriers totalling 40.5M dwt this year, 44% above the 10-year average.
Containership contracting is running in line with the record pace seen in 2024-2025, with 537 vessels totalling 3.4M TEU ordered. The focus has been on tonnage below 8,000 TEU.
Turning to the gas carrier markets, Clarksons has counted 104 LPG carriers totalling 7.7M m³, 14% above the record pace seen in 2024, alongside 69 LNG carriers totalling 11.0M m³, marking the strongest period since the record volumes recorded in 2022.
Chinese shipbuilders continue to lead the market, securing around 75% of vessels, in capacity terms, contracted between January and August. Their share rises to 91% in containership capacity, 90% in bulk carrier capacity and 80% in the crude tanker segment.
South Korean shipbuilders follow with a 15% overall market share, while leading in LPG and LNG carrier contracting, with 65% and 59% of capacity, respectively.




Related to this Story
Events

Maritime Regulations Webinar Week
 16 Dec 2025
 GMT - ONLINE

Floating energy: successfully unlocking stranded gas using FLNGs and FSRUs
24 Feb 2026GMT - ONLINE
© 2026 Riviera Maritime Media Ltd.


